GoHighLevel for financial services: a lead-to-client system with consent built in
GoHighLevel for financial services works as the lead and client follow-up system for insurance agents, mortgage brokers, loan officers and financial advisors: inquiries land in one pipeline, get an instant reply, book a call, and are followed up until they buy, with consent capture, A2P registration and compliance-approved messages designed in from the start. The GoHighLevel Experts builds it at a fixed price of $1,490 to $5,500, live in 2 to 4 weeks.
The GoHighLevel Experts is an independent GoHighLevel setup agency founded by Khyatt, a HighLevel Certified Admin. The team has set up, audited or migrated around 200 GoHighLevel accounts, and insurance brokers are among the business types the team scopes builds for. There’s no financial services case study on this site yet, so this page explains how the team builds it and where the rules matter, without claiming client results.
Key takeaways
- Financial services leads need a fast first reply and long follow-up, and both run automatically in GoHighLevel.
- Texting leads needs written consent captured on the form, A2P 10DLC registration, and STOP handled automatically.
- Broker-dealers and investment advisers have communication and record-keeping rules. Their compliance team approves templates and the archiving setup before launch.
- GoHighLevel doesn’t replace a loan origination system, a policy admin system or an advisor’s portfolio tools. It sits in front of them.
- This page explains how the platform is set up. It isn’t legal or compliance advice.
Why do financial services firms lose leads?
Financial services firms lose leads because the buying decision is slow and the follow-up is fast to break. A mortgage inquiry, an insurance quote request or an advisor consultation often needs several conversations over weeks or months. Leads that don’t hear back quickly, or hear nothing after the first call, go to the next firm. Real estate agents, often on the other side of a mortgage deal, have the same slow decision and fragile follow-up; see GoHighLevel for real estate.
What the team sees most often:
- Purchased and aged leads worked by hand. Insurance and mortgage teams buy leads, call them a few times and stop. There’s no system for the rest of the list.
- Quotes that go quiet. A quote or rate is sent, then nobody follows up until the prospect has bought elsewhere.
- Renewal and review dates in a spreadsheet. Policy renewals, rate-change windows and annual reviews depend on someone remembering them.
- Texts sent without proper consent. Agents text from personal phones or blast lists with no record of who agreed to receive messages.
- Messages nobody approved. A rate, a claim or a product mention goes out in an automated email that compliance never saw.
What does a GoHighLevel build for financial services include?
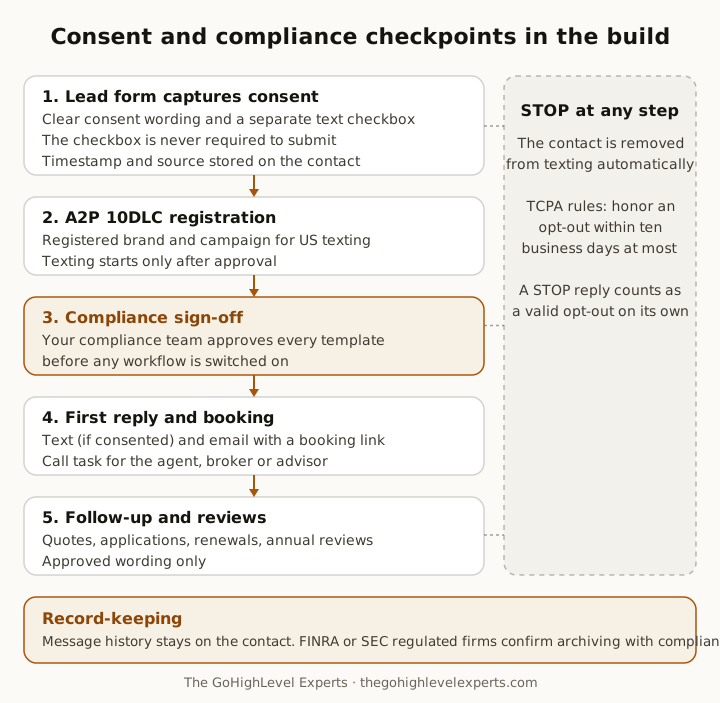
A financial services build includes consent-ready lead forms, an instant first reply with a booking link, a pipeline for each line of business, quote and application follow-up, appointment reminders, renewal or annual review reminders, and referral requests. Message templates go through the firm’s compliance review before they’re switched on.
Lead forms that capture consent
Every form that collects a phone number carries consent wording and a separate checkbox for texts, and the submission stores when and where the person agreed. Under the FCC’s TCPA rules, telemarketing calls or texts sent with an autodialer or a prerecorded voice need prior express written consent, and signing can’t be a condition of buying anything (checked on law.cornell.edu). So the checkbox is never required to submit the form.
A2P 10DLC registration before the first text
US business texting from 10-digit local numbers needs a registered brand and campaign. HighLevel’s help center says manual registration requires clear documentation of how contacts give permission, a public opt-in form, and sample messages that identify the sender and include opt-out language (checked on help.gohighlevel.com). The consent wording on the form and the sample messages have to match what you’ll actually send, so the team agrees them with you before registering. Our A2P 10DLC registration service handles this, including rejections.
Pipelines per line of business
Each line of business gets stages that match how it sells:
| Business | Typical pipeline stages | What GoHighLevel hands off to |
|---|---|---|
| Insurance agency | New lead, contacted, quote sent, application, bound, renewal due | Carrier quoting and policy systems |
| Mortgage broker or loan officer | New inquiry, contacted, pre-approval call, application started, in processing, closed | The loan origination system (LOS) |
| Financial advisor | New inquiry, discovery call booked, plan presented, onboarding, client, annual review | Custodian, planning and portfolio tools |
| Accountant or tax practice | New inquiry, consultation, engagement letter, documents requested, filed, next season | Practice management and tax software |
First reply, booking and reminders
New leads get a short text (if they consented) and an email with a booking link, and the assigned agent, broker or advisor gets a task to call. Calendar bookings send confirmations and reminders, which cuts no-shows on discovery and pre-approval calls. If the AI receptionist answers calls, its script and the facts it can state go through the same compliance review as any other message.
Quote, application and review follow-up
Quotes and half-finished applications trigger follow-up that stops when the person replies or books. Renewal dates, rate-check windows and annual review dates are stored as custom fields, so reminders go out on time without a spreadsheet. After a good outcome, a referral request goes out, where your rules allow it.
What compliance rules affect a GoHighLevel setup in financial services?
The rules that most often shape the build are the FCC’s TCPA rules for texts and calls, A2P 10DLC carrier registration, and, for broker-dealers and investment advisers, FINRA and SEC rules on communications and record-keeping. Mortgage and insurance advertising have their own rules. Your compliance team or attorney decides what applies to your firm.
This isn't legal or compliance advice
The GoHighLevel Experts builds GoHighLevel accounts. It doesn’t give legal or compliance advice and can’t tell you which rules apply to your firm. Use this section to prepare questions for your compliance team, and get their sign-off before anything goes live.
- Texting and calling consent (all firms). Prior express written consent for automated marketing texts and calls, and opt-outs by any reasonable method honored within ten business days. A “STOP” reply counts as a valid opt-out on its own (checked on law.cornell.edu).
- Communications approval (broker-dealers). Under FINRA Rule 2210, a retail communication is any written or electronic communication sent or made available to more than 25 retail investors within 30 calendar days, and an appropriately qualified registered principal must approve each one before it’s used (checked on finra.org). Automated nurture emails can fall into that category.
- Record-keeping (broker-dealers). FINRA’s books and records guidance says SEA Rule 17a-4 requires firms to keep business communications for at least three years, the first two in an easily accessible place, and that this applies to electronic communications on any platform, including a third party’s (checked on finra.org). In 2022 the SEC charged 16 firms over business conducted by text on channels the firms didn’t preserve (checked on sec.gov).
- Investment advisers. SEC-registered advisers have their own marketing rule, adopted in December 2020 and in effect since May 2021 (checked on sec.gov), and their own record-keeping duties.
- Mortgage advertising. Regulation Z requires extra disclosures when a credit ad states certain terms, such as a down payment, a repayment period, a payment amount or a finance charge (checked on consumerfinance.gov). Rate and payment figures in automated messages need checking before they go out.
- Insurance. Insurance marketing is regulated by each state, and carriers often have their own marketing approval rules. Your agency’s compliance contact or carrier decides what wording is allowed.
What this means for the build: the team writes templates in plain, factual language, keeps rates and product claims out unless compliance has approved them, stores consent on every contact, and keeps message history on the contact record. Whether GoHighLevel’s message history is enough for your firm’s archiving, or whether messages also need to go to an approved archiving tool, is a question for your compliance team before launch.
How does The GoHighLevel Experts build GoHighLevel for financial services?
The team builds financial services accounts in the same order as every setup, with a compliance checkpoint added before anything sends: map the sales process and the rules that apply, build the foundations and consent, register A2P, get templates approved, then switch on the workflows and test them.
- Mapping call. The team maps lead sources, who works each lead, the stages from inquiry to client, and which rules your compliance team says apply.
- Foundations and consent. Users and permissions, custom fields (line of business, renewal or review date, consent source), consent wording on every form, a sending domain for email, and a phone number. A2P registration goes in as soon as the consent wording and sample texts are agreed, usually in week 1.
- Templates for approval. Every automated text and email is written and sent to your compliance contact as one document to approve, before any workflow goes live.
- Workflows. First reply, booking and reminders, quote and application follow-up, renewal and review reminders, and referral requests, built with the approved wording only.
- QA and handover. End-to-end tests on real phones, including STOP replies, then a training call, a recorded walkthrough and a PDF manual. Anything the team built that breaks within 6 months is fixed free.
How much does GoHighLevel for financial services cost and how long does it take?
A GoHighLevel setup for a financial services firm costs $1,490 to $5,500 at a fixed price agreed before work starts, and most go live in 2 to 4 weeks. The compliance review of templates is usually what sets the date, so the team sends templates early. A2P 10DLC registration is from $197.
GoHighLevel Setup
$1,490–$5,500
one-time · 2–4 weeks
- Sales process mapped with you first
- Pipelines, calendars, forms and workflows
- Phone, A2P and email domain connected
- Training call, Loom walkthrough and PDF manual
- 6-month build guarantee
A2P 10DLC Registration
From $197
one-time · 7–10 days
- Brand and campaign registration
- Rejection fixes
GoHighLevel Audit
$247
one-time · 48 hours
- Audit call: your setup, sales process and goals
- Detailed audit report: where leads and revenue leak
- Proposed fix with a fixed price
- $247 credited against the build
The HighLevel subscription and usage (texts, calls, email) are paid to HighLevel on top; our GoHighLevel pricing guide breaks them down. If you already run GoHighLevel and aren’t sure the consent and texting setup is right, a $247 GoHighLevel audit checks it. Full scope is on the GoHighLevel setup page, follow-up builds on GoHighLevel automation, and every price is on the pricing page.
When is GoHighLevel the wrong choice for financial services?
GoHighLevel is the wrong choice when your firm’s compliance team requires a CRM with built-in archiving and supervision they’ve already approved, when you need it to be the system of record for loans, policies or client accounts, or when your firm forbids texting clients. In those cases, a vertical CRM or your firm’s approved tools are safer.
- Your broker-dealer or RIA mandates its own tools. Many firms only allow approved, archived channels. Adding GoHighLevel without approval creates the off-channel problem the rules are written to prevent.
- You need a system of record. Loan files, policy records and client account data belong in the LOS, policy system or custodian. GoHighLevel is the front end for leads and follow-up.
- You can’t text clients. Much of GoHighLevel’s value is fast texting. If your firm bans it, a lighter email and booking tool may be enough.
- There’s no time for compliance review. If nobody will approve templates, don’t automate messages yet.
New to the platform? What is GoHighLevel explains it from the start, and our GoHighLevel review covers its strengths and weak spots.
Sources
- Code of Federal Regulations, 47 CFR 64.1200, Delivery restrictions (TCPA rules) (checked )
- HighLevel help center, A2P Campaign Registration: Step by Step Guide and FAQs (checked )
- FINRA, Rule 2210, Communications with the Public (checked )
- FINRA, Books and Records (checked )
- U.S. Securities and Exchange Commission, SEC Charges 16 Wall Street Firms with Widespread Recordkeeping Failures (September 27, 2022)
- U.S. Securities and Exchange Commission, Investment Adviser Marketing (checked )
- Consumer Financial Protection Bureau, Regulation Z, 12 CFR 1026.24 Advertising (checked )
FAQ
Can financial services firms use GoHighLevel?
Yes, for lead intake, booking, follow-up and client reviews. Firms regulated by FINRA or the SEC also need to know whether texts and emails sent from GoHighLevel are captured and kept the way their record-keeping rules require, so their compliance team should approve the setup before launch.
Is GoHighLevel FINRA or SEC compliant?
No software is compliant on its own. FINRA and SEC rules apply to the firm and how it communicates. A GoHighLevel build can capture consent, keep message history and route templates for approval, but the firm's compliance team decides whether the account and its archiving meet the firm's obligations.
Do I need consent to text leads from GoHighLevel?
For marketing texts sent with automated systems, the FCC's TCPA rules require the person's prior express written consent, and a STOP reply must be honored within ten business days. US business texting from 10-digit numbers also needs A2P 10DLC brand and campaign registration.
How much does a GoHighLevel setup for an insurance agency or mortgage broker cost?
The GoHighLevel Experts sets up GoHighLevel at a fixed price of $1,490 to $5,500, agreed before work starts, and most builds go live in 2 to 4 weeks. A2P 10DLC registration is from $197. The HighLevel subscription and usage are paid to HighLevel separately.